Moving to Malta from the UK has become a popular choice for British expats. Many want a better quality of life, lower living costs than parts of the UK and a Mediterranean climate. Others want a well-regulated base within Europe for their finances. English is an official language, and the island has a large expat community and good flight connections. As a result, Malta appeals to retirees, entrepreneurs, remote workers and mobile professionals alike.
For many UK nationals, Malta offers a good balance between European lifestyle and familiarity. The island combines warm weather, affordable healthcare and low crime with a relaxed pace of life. It also has a sophisticated financial services sector and several residency options.
However, Brexit ended freedom of movement for British citizens in the EU. So UK expats now need the right residency permit or visa before moving to Malta long-term. The good news is that Malta still offers several routes, depending on your circumstances, income and long-term goals.
In this guide, we explore the main visa and residency options for UK expats moving to Malta. These include residency by investment, the digital nomad permit, employment permits and retirement schemes.
If you have any questions, please contact me through my contact page. For more residency options, view my Residency service page.
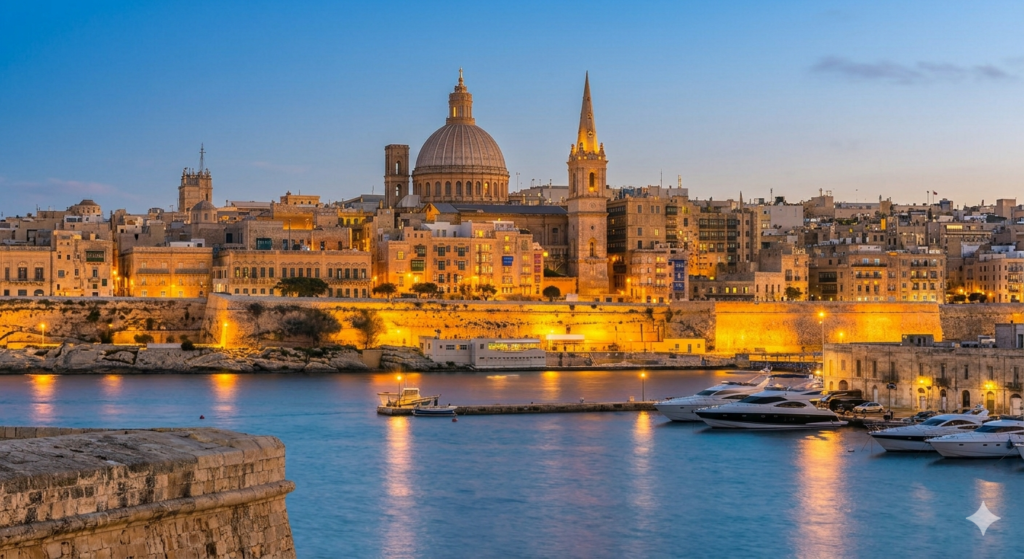
Why UK Expats Are Moving to Malta
Over the last decade, Malta has become one of Europe’s leading relocation hubs. In many European countries, language barriers and bureaucracy can be a challenge. Malta, by contrast, offers a smoother transition for British nationals.
Some of the main reasons UK expats are relocating to Malta include:
- English is an official language of business and government.
- Warm Mediterranean climate with over 300 days of sunshine annually.
- Relatively low living costs compared with London and parts of Western Europe.
- Planning opportunities for international residents.
- Strong banking and financial services sector.
- Access to European travel and lifestyle.
- Excellent healthcare system and private medical facilities.
- Established expat communities and international schools.
Malta is especially popular with retirees, remote workers, consultants and online business owners. It also attracts high-net-worth individuals who want a second residency in Europe.
Malta Visa and Residency Options for UK Expats

Since Brexit, Malta treats UK nationals as third-country nationals. This means you need the correct residency status before moving to Malta permanently.
The best visa route depends on your plans. For example, are you retiring, investing, working remotely, starting a business or taking a local job?
The Malta Permanent Residence Programme (MPRP)
One of the most popular options for affluent expats is the Malta Permanent Residence Programme (MPRP). The scheme lets non-EU nationals secure long-term residency in Malta through investment and a financial contribution.
The programme grants permanent residency rather than citizenship. Even so, it offers flexibility and long-term security for families settling in Malta.
Key Benefits of the MPRP
Successful applicants benefit from:
- Permanent residency rights in Malta.
- The ability to include dependent family members.
- Visa-free travel throughout the Schengen Area.
- No mandatory minimum stay requirement.
- Access to Malta’s stable legal and financial system.
Unlike some European residency programmes, the MPRP does not require you to live in Malta full time to keep your status.
Financial Requirements
Applicants must demonstrate sufficient financial resources, including either:
- Capital assets of at least €500,000, with €150,000 held in financial assets, or
- Total assets of €650,000, with at least €75,000 in financial assets.
In addition, applicants must buy or rent a qualifying home and keep it for at least five years:
- Buy a property worth at least €375,000, or
- Rent a property with a minimum annual rent of €14,000.
Under the rules reformed in 2025, there are also government contributions and fees. According to Residency Malta, these include:
- A €37,000 government contribution, whether you buy or rent.
- A €60,000 non-refundable administration fee.
- €7,500 for each adult dependant (other than a spouse).
- A €2,000 donation to a registered Maltese NGO.
Applicants must also hold comprehensive private medical insurance and pass due diligence and criminal background checks. Fees change from time to time, so always check the latest figures before applying.
Is the MPRP a Route to Citizenship?
The MPRP itself does not provide citizenship. However, some long-term residents with strong ties to Malta may later qualify through naturalisation. This depends on the eligibility rules and government discretion.
European institutions have also scrutinised citizenship-by-investment schemes closely. So it is more important than ever to choose a long-term, compliant residency route rather than a “golden passport”.
The Malta Digital Nomad Visa
Malta has become increasingly attractive to remote workers through the Nomad Residence Permit. Many people call it the Digital Nomad Visa.
This route suits non-EU nationals who work remotely for overseas employers or clients while living in Malta.
Who Is Eligible?
The permit is available to individuals who:
- Work remotely for a company registered outside Malta.
- Operate a business serving international clients.
- Work as freelancers or consultants with non-Maltese income.
- Earn at least €42,000 a year gross (about €3,500 a month). This threshold applies to applications made since April 2024.
Applicants must also demonstrate they can continue working remotely while residing in Malta.
Benefits of the Digital Nomad Visa
The Nomad Residence Permit has become particularly popular among younger professionals and location-independent entrepreneurs because it offers:
- The ability to legally live in Malta while working remotely.
- Attractive tax treatment on foreign-sourced income.
- Access to Malta’s lifestyle and international community.
- A relatively straightforward application process.
Residency Malta usually issues the permit for one year at first. You can then generally renew it, up to a maximum of four years, as long as you still meet the criteria.
To maintain renewals, applicants must usually spend a minimum amount of time physically present in Malta each year.
Important Considerations
The Digital Nomad Visa is flexible. However, it does not lead directly to permanent residency or citizenship. Many expats use it as a stepping stone while they weigh up longer-term plans.
For UK entrepreneurs, consultants and online business owners, Malta can still offer lifestyle and tax advantages over staying UK resident. Take specialist international tax advice first, so the move is set up correctly.
Employment and Professional Work Permits in Malta
UK nationals moving to Malta for a local job will usually need a Single Permit. This combines work authorisation and residency rights.
Employers in Malta generally sponsor these applications, and approval depends on:
- Employment contract details.
- Salary level and qualifications.
- Evidence that the employer cannot easily fill the role locally.
- Professional experience and skills.
Malta’s economy continues to attract foreign professionals in sectors such as:
- Financial services.
- Gaming and iGaming.
- Technology and fintech.
- Cryptocurrency and blockchain.
- Hospitality and tourism.
- Healthcare.
For highly skilled professionals, certain fast-track schemes may also be available.
Retiring to Malta from the UK
Malta has long been one of the most attractive retirement destinations for British nationals. The combination of climate, healthcare, lower costs, and English-speaking infrastructure makes it particularly appealing for retirees seeking a Mediterranean lifestyle.
The Malta Retirement Programme offers special tax treatment to qualifying retirees. Their pension must be their main source of income.
Applicants generally need to:
- Purchase or rent a qualifying property in Malta.
- Receive stable pension income.
- Hold private health insurance.
- Spend a minimum period in Malta annually.
For retirees with UK pensions, SIPPs, ISAs, investments or rental income, careful tax planning before moving to Malta is essential. In particular, the timing of your move can affect how capital gains are taxed.
Is Moving to Malta Still a Good Option for UK Expats?
Despite tighter European immigration rules post-Brexit, Malta remains one of the most accessible and attractive destinations for British expats.
Its climate, English-speaking environment, financial infrastructure and residency routes still appeal to retirees, investors and mobile professionals.
However, immigration rules, tax frameworks and residency programmes keep evolving. EU scrutiny of investment migration also continues. So make sure you get up-to-date, regulated advice before making major financial or residency decisions.
For many UK nationals, Malta offers a lifestyle upgrade. It can also be a chance to organise their finances more efficiently while staying connected to Europe.
What Has Changed for UK Nationals Moving to Malta in 2026?
For British expats, the rules for moving to Malta have changed a lot over the last two years. Malta remains one of Europe’s most attractive destinations for UK nationals. However, the process is now far more structured, because of Brexit, new Schengen border systems and closer EU scrutiny of residency and citizenship schemes.
The EU Entry/Exit System (EES)
One of the most important practical changes is the EU Entry/Exit System (EES). It became fully operational across the Schengen Area on 10 April 2026. The system replaces passport stamping for non-EU travellers, including British citizens. Instead, it records every entry and exit electronically. So if you travel often between Malta, the UK and other countries, Schengen day-counting matters far more than before. In short, you can no longer rely on rough estimates of your time in Europe, because the system tracks it automatically.
The End of Malta’s Citizenship by Investment
Another major development came on 29 April 2025. On that date, the Court of Justice of the European Union ruled against Malta’s investor citizenship scheme. The decision reinforced Europe’s shift away from “buying” citizenship. Instead, the focus is on genuine links, lawful residence and long-term integration. For UK nationals, this changes how to view Malta. It is no longer a simple citizenship-by-investment destination. Rather, it is a residency, lifestyle and long-term planning jurisdiction, where any future citizenship depends on genuine residence and integration over time.
Changes to the MPRP and Tax Programmes
Malta also reformed the Malta Permanent Residence Programme (MPRP) in 2025. The changes covered pricing, property rules and temporary residence during the application. As a result, UK nationals should not rely on older articles or outdated programme rules. Careful planning around timelines, accommodation, healthcare cover and documents now matters more than ever.
Malta’s Global Residence Programme also continues to attract British expats. The programme offers a 15% tax rate on qualifying foreign income remitted to Malta, with a minimum annual tax payment. However, this makes pension planning, remittance planning and the timing of your UK tax exit central to the move. For many UK nationals, the planning done before becoming Maltese tax resident matters more than the physical move itself.
Why Planning Matters More Than Ever
The broader reality is that moving to Malta is no longer just an “easy English-speaking move abroad”. Malta still offers English-speaking administration, British legal influence, low crime, good healthcare and sophisticated financial services. However, the relocation process has become more technical and compliance-driven. Each route needs the right programme, proper documents, compliant accommodation, healthcare cover and long-term financial planning.
Compared with many European countries, Malta remains very accessible for UK nationals. Its legal system, banking, administration and everyday communication all feel familiar. For many people, Malta also feels easier than much of Southern Europe, because language barriers are minimal and British influence runs deep in its legal and professional systems.
However, easier does not mean casual. The UK nationals who settle most successfully prepare thoroughly before leaving Britain. They do not try to fix residency, pension, tax and compliance issues afterwards. For most British expats, the strongest approach is a residency-first plan from day one. That normally means:
- confirming the right residency route first;
- planning your UK tax residency exit carefully;
- reviewing pensions and investments before you go;
- securing qualifying accommodation;
- arranging compliant healthcare cover; and
- preparing all your documents before the move.
For retirees, entrepreneurs, remote workers and wealthy families, Malta remains one of Europe’s strongest relocation destinations. It offers an excellent mix of lifestyle, European access and financial planning opportunities. However, poorly planned moves now face more delays, rejected applications, unexpected tax bills and costly compliance problems. In most cases, proper planning before leaving the UK would have prevented them.
Moving to Malta can be an excellent long-term decision for UK expats. It combines a Mediterranean lifestyle, English-speaking administration, good healthcare and European access. However, do not underestimate the financial, administrative and compliance work involved in becoming properly resident in Malta after Brexit.
Where the Biggest Risks Lie When Moving to Malta
In most cases, the biggest risks have little to do with lifestyle or integration. Instead, they usually involve residency approvals, the timing of your UK tax exit, remittances, pensions, healthcare cover, accommodation rules and poorly coordinated finances.
Many British expats assume the process is simple because Malta feels familiar. Malta is certainly easier than many European countries. Still, residency applications and tax planning need careful preparation. Even small mistakes with documents, proof of funds, accommodation, health insurance or tax planning can cause delays and extra costs. Some can also create long-term compliance problems that are hard to fix later.
The UK nationals who settle most successfully treat moving to Malta as a long-term planning project, not just a lifestyle move.
Challenges for UK Nationals Moving to Malta
Bureaucracy and Processing Times
One of the most common frustrations for expats moving to Malta is bureaucracy and timing. Malta’s immigration system is fairly accessible compared with many EU countries. However, processing times can vary a lot, for residency permits, tax registration, driving licence transfers and other public services alike. Much depends on the quality of the application and the time of year. In addition, incomplete or incorrect documents can cause delays that hold up the whole move.
Professional help with your application can reduce these risks. It helps make sure your residency filings, healthcare, source-of-funds evidence and accommodation are compliant from the start.
Competition for Property
The property market is another important consideration. Prime areas such as Sliema, St Julian’s and Valletta see strong demand from local and international buyers and tenants. Affluent expats and remote workers in particular compete for the best homes. So if you are planning a move, organise financing, proof of funds and residency documents early, to avoid missing suitable properties.
Also, think about property alongside residency rules, tax residency, remittances and your long-term financial goals. Treating it as a standalone lifestyle purchase is a common mistake.
Everyday Adjustments
Malta can offer excellent lifestyle value compared with many parts of the UK and Western Europe. However, imported UK goods and international brands often cost more on the island. Over time, many residents switch to local suppliers and seasonal produce. As a result, they often cut their living costs while enjoying a better quality of life.
Another adjustment for many UK nationals is the Mediterranean pace of life. Administration, appointments and business culture can feel slower and less time-sensitive than in Britain. So a successful move needs flexibility, patience and realistic expectations about timelines.
Safety in Malta
In terms of safety, Malta remains one of the safer countries in Europe. Petty theft can occur in busy tourist areas, but violent crime is comparatively low. For retirees, families and mobile professionals, safety, climate, healthcare and English-speaking services remain some of Malta’s strongest long-term attractions.
For many British expats, Malta offers an excellent balance between lifestyle and financial efficiency. However, the most successful moves rest on careful planning before leaving the UK. This applies especially to residency, pensions, tax, healthcare and long-term wealth management.
Cost of Living in Malta for UK Expats
Understanding the cost of living is an important part of moving to Malta. The island has a very different cost profile from both the UK and many other Mediterranean destinations.
For most British expats, the attraction is not simply that Malta can be cheaper than the UK. The real advantage is the overall balance. Day-to-day costs are manageable, and you also get planning opportunities, English-speaking services, safety, good healthcare and easy access to Europe.
For retirees, entrepreneurs, remote workers and families, Malta can offer excellent value when you plan the move well. However, you still need a careful budget, especially for accommodation, healthcare, residency property rules, schooling and long-term financial planning.
The UK nationals who settle best look at living costs, pensions, remittances, tax residency and property together, rather than as separate issues.
Housing and Utilities
Accommodation is usually the largest expense for British expats moving to Malta. Prices vary widely by location. Premium coastal areas such as Sliema, St Julian’s and Valletta cost much more than inland towns or quieter parts of Gozo.
Many expats choose these areas for their international atmosphere, restaurants, waterfront living and closeness to business districts. However, you can find more affordable options outside the main coastal zones if you want lower costs or a quieter lifestyle.
Utility bills are generally moderate compared with parts of the UK. However, electricity costs can rise noticeably in summer because of heavy air-conditioning use. Internet, water and mobile services are typically reliable and reasonably priced.
Daily Living Costs
For everyday expenses, Malta can offer very good value compared with many British cities. Local and seasonal produce is usually affordable. However, imported UK products and international brands often cost more because of shipping and import costs.
Over time, many British expats adapt to local shopping habits, which can reduce living costs considerably.
Dining out is also one of Malta’s lifestyle advantages. Restaurants, cafés, and waterfront dining are generally more affordable than in much of the UK, while still offering excellent quality and variety. For many expats, the ability to enjoy a more social outdoor lifestyle year-round becomes one of the biggest quality-of-life improvements after relocating.
Transport and Lifestyle
Public transport in Malta is relatively cheap, and many residents use the bus network instead of running a large car. Because Malta is so compact, journeys are short compared with most UK cities. This can cut commuting costs significantly.
Gyms, beach clubs, leisure activities and entertainment are also competitively priced compared with many European destinations, especially given the climate and outdoor lifestyle.
For many UK expats, the overall cost profile in Malta represents strong value when balanced against the island’s combination of safety, weather, healthcare, and quality of life.
Healthcare in Malta for UK Expats
Healthcare quality is one of the main reasons British retirees and families choose Malta. The island combines a strong public system with modern private facilities, and most healthcare professionals speak English.
For UK nationals, this brings familiarity and reassurance. Communication is easy, and standards are generally high by international standards.
However, do not assume you get healthcare access automatically on arrival. Your residency status, private insurance and programme rules all matter in the early stages of your move.
The best relocation plans therefore coordinate residency, healthcare cover, pensions and finances before the move.
Public Healthcare in Malta
Residents who pay into Malta’s social security system may gain access to public healthcare, including GP appointments, hospital treatment and specialist care. Malta’s public system has a good reputation for efficiency. However, as in many European countries, you may face waiting times for some procedures.
For retirees and long-term residents, it is important to check eligibility before moving to Malta, to avoid gaps in cover.
Private Healthcare and Insurance
Many British expats choose private medical insurance even when they qualify for public healthcare. It offers faster treatment, more flexibility and access to private hospitals and specialist clinics.
Private healthcare in Malta often costs considerably less than in many other international locations. As a result, comprehensive cover can be more affordable for retirees and mobile professionals.
Policies range from basic inpatient cover to comprehensive international medical plans. Many expats also review healthcare alongside their wider estate and family protection planning.
Education and Schooling for UK Families
For British families moving to Malta, education is often one of the most important long-term considerations. Malta’s schools draw heavily on British education traditions, and English is widely used in both public and private schools.
This makes the transition much easier for British children than in many other European destinations.
Malta also offers flexibility for mobile families. Many private and international schools follow British curricula or the International Baccalaureate, which helps if you move again later.
Ideally, make schooling part of your wider relocation plan. After all, the school you choose often shapes where you live, how you commute, your budget and your long-term residency plans.
Public Education in Malta
Public schools in Malta are free for residents and generally offer good standards. Teachers use both English and Maltese. However, many British families still choose private schools to stay closer to the UK curriculum, especially if they may return to Britain later.
Private and International Schools
Malta has a strong network of private and international schools offering British, American and International Baccalaureate programmes. Expat families like them for their smaller classes, international communities, modern facilities and wide range of activities.
Demand for places at leading schools can be high. So many British families research availability and waiting lists well before moving to Malta.
Higher Education
Malta also offers respected higher education, including the University of Malta, which teaches many undergraduate and postgraduate degrees in English.
For families planning to settle long-term, English-language education, European access and international schools remain some of the island’s strongest advantages.
Cost of Living in Malta: Typical Monthly Costs
| Expense | Average Monthly Cost in Malta |
| 1-Bed Apartment (City Centre) | €900 – €1,400 |
| 1-Bed Apartment (Outside Centre) | €700 – €1,000 |
| 3-Bed Apartment (City Centre) | €1,500 – €2,800 |
| Utilities (Electricity & Water) | €80 – €180 |
| Internet | €25 – €45 |
| Mobile Phone Plan | €15 – €30 |
| Weekly Groceries (1 Person) | €50 – €80 |
| Monthly Groceries (Couple) | €350 – €500 |
| Meal at Mid-Range Restaurant | €18 – €30 |
| Coffee | €2 – €4 |
| Monthly Public Transport Pass | €26 – €30 |
| Gym Membership | €30 – €100 |
| Private Health Insurance | €25 – €125 per month |
| Private School Fees | €3,000 – €12,000+ per year |
| International School Fees | €8,000 – €25,000+ per year |
| Taxi (Short Journey) | €10 – €20 |
| Single Person Monthly Budget | €1,300 – €2,500+ |
| Couple Monthly Budget | €2,500 – €4,000+ |
| Family of Four Monthly Budget | €4,000 – €7,000+ |
These are indicative 2026 ranges only. Prices change and vary by location, so check current costs before you budget.
Buying Property in Malta for UK Expats
Buying property in Malta is often about more than a home in the sun. For many UK nationals, it becomes central to residency planning, retirement planning and a secure European base after Brexit.
Malta’s property market has attracted British buyers for many years. Limited land, strong international demand, English-speaking services and residency-linked property rules all support demand in key areas.
However, one of the biggest mistakes UK buyers make is treating Maltese property purely as a lifestyle purchase. They overlook the tax, residency, inheritance, financing and remittance implications. A poorly planned purchase can lead to extra costs, residency problems or tax inefficiencies that are hard to unwind.
The most successful UK expats treat Malta property as part of a coordinated plan for moving to Malta, rather than an emotional decision alone.
Why UK Expats Buy Property in Malta
For many British nationals, owning property in Malta offers stability, residency support and lifestyle benefits within the EU. Like any property, however, its value can fall as well as rise.
Malta continues to attract overseas buyers because it combines:
- Strong rental demand.
- Limited housing supply.
- International buyer interest.
- European accessibility.
- Political stability.
- English-speaking legal and banking systems.
For retirees, remote workers, entrepreneurs and families, owning property can also support a residency application and give more flexibility for future plans in Europe.
Popular Types of Property in Malta
The Maltese property market offers a wide range of options, depending on your lifestyle, residency goals and budget.
Apartments
Modern apartments remain the most popular choice for UK expats, especially in coastal areas such as Sliema, St Julian’s and Valletta. Professionals, tourists and international residents all rent in these areas. So apartments there can suit both lifestyle and rental income goals.
Many newer developments offer sea views, gyms, pools, concierge services, and proximity to restaurants, marinas, and business districts.
Villas
Buyers often look for luxury villas in areas such as Madliena, Mellieħa and parts of northern Malta. These homes often include private pools, larger plots, gardens and panoramic views.
For high-net-worth individuals and retirees seeking privacy and long-term family living, villas remain one of the most prestigious property categories on the island.
Townhouses and Heritage Properties
Traditional Maltese townhouses and heritage homes remain popular with buyers who want character. Valletta and Mdina, for example, have beautifully restored historic homes with strong architectural appeal.
These properties often attract buyers looking for unique homes rather than purely investment-focused real estate.
The Best Areas to Buy Property in Malta
Different regions of Malta appeal to different types of expats depending on budget, lifestyle, and investment priorities.
Sliema and St Julian’s remain among the most popular areas for British expats. They offer waterfront living, restaurants, an international atmosphere and strong rental demand. As a result, they suit professionals, remote workers and landlords.
Valletta continues to attract premium buyers thanks to its history and high-end developments. The capital has become increasingly popular with international and lifestyle buyers.
Mellieħa appeals more to families and villa buyers seeking quieter surroundings, larger properties, and proximity to beaches.
Gozo attracts retirees and lifestyle buyers who want lower prices, less density and a slower pace of life. Residents there still benefit from Malta’s wider residency and financial framework.
Property Prices in Malta
Property prices in Malta vary considerably depending on location, property type, residency demand, and international buyer activity.
As a general guide:
| Property Type | Average Price Range |
| Apartments | €250,000 – €500,000+ |
| Townhouses | €400,000 – €1.2M+ |
| Villas | €800,000 – €3M+ |
Indicative ranges only – prices vary widely by location and change over time.
Prime coastal areas such as Sliema, St Julian’s, and Valletta command significantly higher prices because of their lifestyle appeal, limited supply, and strong rental demand.
Inland towns and Gozo often offer more affordable entry points for UK retirees and lifestyle buyers.
The Property Buying Process in Malta
For UK nationals, buying property in Malta involves more than agreeing a price. Ideally, review residency rules, financing, inheritance planning and tax before you commit.
The process starts with finding the right property. Look beyond lifestyle to residency rules, long-term tax planning, rental potential and resale flexibility.
Once you choose a property, you will usually sign a promise of sale agreement, known locally as a konvenju. At this stage, legal checks, financing and due diligence become extremely important.
Before completion, make sure your notary and lawyer have checked ownership rights, permits, inheritance issues, tax and regulatory compliance.
Ideally, sign the final deed only once your residency and tax planning are in place.
Legal Rules for UK Buyers After Brexit
Since Brexit, British buyers in Malta generally fall under the Acquisition of Immovable Property (AIP) rules, unless they buy within a Special Designated Area (SDA).
In many cases, UK buyers require an AIP permit when purchasing property outside designated zones.
Special Designated Areas let non-EU nationals buy with fewer restrictions. As a result, they have become increasingly popular with British buyers.
Additional Costs When Buying Property
UK buyers should also budget for additional acquisition costs beyond the property purchase price itself.
These commonly include:
| Cost Type | Typical Amount |
| Stamp Duty | Around 5% |
| Notary Fees | Approximately 1–2% |
| Legal & Registration Fees | €600 – €1,000+ |
Factor these costs into your budget before you commit.
Malta Tax for UK Expats
Understanding Malta’s tax system is one of the most important parts of moving to Malta from the UK. Malta can be a tax-efficient place to live. However, that depends on getting your residency, domicile, pensions, remittances, investments and UK exit timing right before you move.
One of the biggest mistakes is assuming Malta is automatically a “low-tax” country. In reality, its tax system is attractive but highly technical. The benefits of Malta’s residence-and-domicile rules depend on how you arrange your foreign income, pensions, offshore assets and remittances before you become Maltese tax resident.
For many British expats, the most expensive tax mistakes happen before the move, not after it. Poor planning around pension withdrawals, investment sales, remittances or UK residency timing can create unexpected tax bills that are hard to correct later.
So the best plans coordinate residency applications, pensions, investments, inheritance planning, future income and tax residency well before the move.
Malta’s tax year runs from 1 January to 31 December, and you generally file your return during the following year. Once you become tax resident, proper reporting and compliance are extremely important.
Malta’s Residence and Domicile Tax System
One of the reasons Malta attracts internationally mobile individuals is its residence-and-domicile tax framework.
For many UK expats who become resident but are not domiciled in Malta, foreign income is generally taxable only if you remit it to Malta. In addition, foreign capital gains are generally not taxable in Malta, even if remitted, provided certain conditions are met.
This creates significant planning opportunities for retirees, entrepreneurs, remote workers and wealthy individuals with international assets and income.
However, remittance planning becomes critically important. Remitting foreign income in the wrong way, restructuring pensions at the wrong time or selling assets after you become resident can all cause avoidable tax problems. Take specialist cross-border tax advice before you act.
Income Tax in Malta
Malta has a progressive income tax system for individuals. Rates range from 0% to 35%, depending on your income and status.
In general, Malta taxes residents who are not domiciled there on:
- Income arising in Malta.
- Foreign income remitted into Malta.
Non-residents normally pay Maltese tax only on Maltese-source income.
For many UK expats, the difference between foreign income and foreign capital gains is very important. Different rules can apply, depending on the type of income and how you transfer money into Malta.
Capital Gains Tax in Malta
Capital gains tax rules in Malta vary depending on the type of asset involved.
For Maltese property, tax is generally a final tax on the transfer value rather than on the actual gain. The standard rate is commonly 8%, although other rates apply in some cases.
Some exemptions apply, for example when the property has been your main home for a qualifying period.
For shares and other securities, the tax treatment depends on your residency and domicile status, where the asset is located and whether you remit the gain.
For UK expats moving to Malta, the timing of any UK asset sales is often an important part of pre-move planning. Remember that UK rules on temporary non-residence can also apply if you return to the UK within five years.
Dividend Tax and Investment Income
Investment income planning is another important area for British expats moving to Malta.
Foreign dividends are generally taxable in Malta only if remitted, for residents who are not domiciled there. Malta also has a large network of double taxation treaties, which can reduce withholding taxes and prevent double taxation on international investments.
So Malta’s tax system can suit internationally diversified investors, especially when they plan their investments, platforms and remittances properly before the move.
Inheritance Tax and Estate Planning
One of Malta’s most attractive features for wealthy individuals and retirees is that it has no inheritance tax or estate duty as such.
This makes Malta appealing for long-term family wealth planning.
However, property transfers on death can still trigger duty in Malta. Also, UK inheritance tax does not automatically stop when you leave Britain. Since 6 April 2025, UK IHT on worldwide assets depends on long-term UK residence rather than domicile. So many UK nationals stay within its scope for several years after moving abroad. In addition, from 6 April 2027 most unused pension funds will count towards your estate for UK inheritance tax.
As a result, review your estate planning alongside residency and tax planning before moving overseas.
Blogs I’ve written to help with IHT for expats:
Get my support and advice on your estate and understand your options: Estate Planning for Expats.
Corporate Tax in Malta
Malta’s corporate tax system is well known for its flexibility and its shareholder refund system.
The headline corporate tax rate is 35%. However, Malta operates a full imputation system with shareholder refunds, which can reduce the effective rate significantly in certain circumstances.
For entrepreneurs, consultants and mobile business owners, Malta can therefore offer useful structuring options when set up correctly and compliantly.
However, international rules on substance, management, control and anti-avoidance have tightened significantly. So any company structure needs careful professional oversight.
VAT in Malta
Malta’s standard VAT rate is 18%, with reduced rates for some sectors, such as accommodation and certain goods and services.
If you run a business in Malta, you may need to register for VAT once you exceed the thresholds, especially for trading or local services.
For entrepreneurs moving from the UK, it is wise to review VAT registration and cross-border reporting before you start trading in Malta.
Double Taxation Agreements
Malta has signed more than 70 double taxation treaties, including a comprehensive agreement with the United Kingdom.
These agreements help prevent the same income being taxed twice. They can also reduce withholding taxes on dividends, interest, royalties and pensions.
For UK expats, understanding how the UK–Malta treaty applies to pensions, investment income and residency is often central to long-term tax planning. For example, UK government service pensions usually remain taxable in the UK.
Global Residence Programme (GRP)
The Global Residence Programme (GRP) remains one of Malta’s most popular options for mobile UK nationals.
The programme applies a 15% tax rate to qualifying foreign income remitted to Malta, with a minimum annual tax of €15,000. For some retirees and wealthy individuals, this offers a clear and predictable tax position.
However, it only works well when your pensions, investments, remittances and UK tax residency are coordinated before the move.
Malta Retirement Programme
The Malta Retirement Programme is aimed mainly at retirees who want favourable tax treatment of their pension within an English-speaking EU country.
For UK pension holders, careful planning around withdrawals, remittances and future inheritance tax remains essential before you join the scheme.
High Net Worth and International Residency Structures
Malta also remains attractive for wealthy, internationally mobile people who want European residence and remittance-based taxation.
However, compliance expectations are now much higher than in previous years. Long-term residency increasingly requires genuine substance, clean documents, healthcare cover and careful coordination between your UK and Maltese tax positions.
For most British expats, the best results come from treating Malta not just as a low-tax country, but as part of a long-term wealth and residency plan put in place before leaving the UK.
Summary: Moving to Malta in 2026
Moving to Malta from the UK in 2026 offers a blend of Mediterranean lifestyle and financial planning opportunities. These include the Global Residence Programme (GRP) and its 15% tax rate on remitted foreign income. However, the UK will bring most unused pensions into inheritance tax from April 2027, and overseas schemes such as QROPS are generally also in scope for people who are long-term UK residents. So moving abroad, or moving a pension, does not automatically remove UK IHT. With careful planning around remittances, UK tax exit and post-Brexit residency rules, Malta can be an excellent long-term base. Take regulated, specialist advice before you act.
Watch: Moving to Malta Explained
Moving to Malta: FAQs
It depends on your income, assets and plans. For wealthier expats, the Global Residence Programme (GRP) is often considered. It applies a 15% tax rate on qualifying foreign income remitted to Malta, with a minimum annual tax of €15,000. It can suit people with significant dividend or pension income, because it gives a predictable tax position. Retirees may also look at the Malta Retirement Programme. Take specialist tax advice before you choose.
Generally, no. From 6 April 2027, most unused pension funds will count towards your estate for UK inheritance tax. Qualifying overseas schemes, including QROPS, are also expected to come within the charge for people who are long-term UK residents. So a transfer should not be made just for IHT reasons. A transfer can also trigger the 25% overseas transfer charge in some cases. Separately, under the UK–Malta tax treaty, private pension income is usually taxed where you live, while UK government service pensions usually stay taxable in the UK. Take regulated advice before you transfer any pension.
Malta taxes residents who are not domiciled there (which includes most UK expats) on income arising in Malta and on foreign income they remit (bring) into the country. Foreign capital gains are generally not taxable in Malta, even if remitted. However, the rules have conditions, a minimum tax can apply in some cases, and remitting money in the wrong way can create tax. So plan your remittances carefully with a specialist adviser.
Thinking about moving to Malta? Book a discovery call and we can review your pensions, investments and tax position before you go.
This article is for general information only and is not tax, legal or financial advice. Tax rules and residency programmes change, so check the latest position and take specialist advice for your circumstances. The value of investments can fall as well as rise. Capital at risk.
Free tools for this topic
All free tools →Free, no sign-up, nothing stored.
Henry Temple-Baxter
Henry Temple-Baxter is the founder of Investments for Expats and is CISI Level 4 qualified. A long-term expat himself, he has lived and worked in Kuala Lumpur, Beijing, Bangkok, Hong Kong and Ho Chi Minh City. He set up the firm in 2018 to give UK expats fee-only, transparent advice on pensions, tax and investing abroad.
This guide is general information, not personal advice. Tax rules can change and their effect depends on your circumstances. Capital at risk.