One of the big questions which are on many peoples minds, is how much do I need to retire? I have been asked this a lot of times along with how much is going to be enough for me?
This does vary on where you are living and how you live your life and the age at which you ultimately choose to retire. However, two U.K. based studies have done studies based on research with 7000 questionnaires on how much you will need to retire in 2021. They were undertaken by Which? and Key Retirement and I will link to them throughout the article.
What did they find, Which? states that a 26,000 GBP a year cost is needed for a single person, Which? defined as a modest retirement. While, 2021, research from Key Retirement states that 21,663 GBP average retirement income is still not enough to pay the essentials.
This article will look at what the research shows in more depth as to what is needed and look at ways to enable a retirement at set age groups if you haven’t already.
* This is U.K based but will have some relevance to most western countries.
What do retirees earn?
As of 2021, pensioners averaged 1,000 GBP a year income, with the vast majority of this coming up from the state pension. Although Key Retirements does state that this near 4% increase from 2020 is also down to alternative factors such as the wealthier are retiring younger.
It also stated, unsurprisingly, that homeowners were on average 1,729 GBP better off than the average pensioners and renters 5,127 worse off annual income than the average retirees in Key Retirements research.
Furthermore, it went on to show good news for couples, who are also stated as being better off than singles.
How much do retirees spend on their lifestyle?
The Which? study conducted in 2021, ranged that a two-person luxury lifestyle would cost 41,000 GBP and a single essential on 13,000 GBP. This is demonstrated in the table below.
Table 1 Show the findings of Which? study on spending in pensioners

Where is this money going?
Here’s a breakdown of how retirees are spending their money in order to fund their lifestyle, it shows that luxury pensioners are spending more money on both long haul, short-haul holidays and leisure. While essentials retirees are making do with the holidays and the leisure activity.
Table 2- Shows the difference between spending habits.
| Essential | Comfortable | Luxury | |
| Long haul holidays | – | – | £5,652 |
| European holidays | – | £3,588 | £3,588 |
| New car costs | – | – | £4,438 |
| Groceries | £2,256 | £2,256 | £2,256 |
| Housing costs | £2,592 | £2,592 | £2,592 |
| Insurance | £1,824 | £1,824 | £1,824 |
| Transport | £1,524 | £1,524 | £1,524 |
| Utilities | £1,688 | £1,668 | £1,668 |
| Recreation/Leisure | – | £1,188 | £1,188 |
| Household goods | £1,044 | £1,044 | £1,044 |
| Charity | – | £1,308 | £1,308 |
| Leisure membership | – | – | £1,044 |
| Health | £972 | £972 | £972 |
| New clothes | £696 | £696 | £696 |
| Tobacco/Alcohol | – | £756 | £756 |
| Meals out | – | – | £744 |
| Total | £12,596 | £19,416 | £31,294 |
Source: Which?
How much is needed for retirement is dependent on relationship status, lifestyle factors and homeownership as seen in the tables above. But, what is needed for retirement and what budgets are actually showing is very different.
This is shown by Which? in table 3, on the income needed and spending gap both in weekly and annual amounts.
Living with the biggest discrepancy are luxury couples who are down 425 GBP a week while single essential come best off with plus 113 GBP better off.
Table 3- By Which? shows the discrepancy of each lifestyle, level for single and married couples and the weekly and annual discrepancy.
| Budget | Annual income needed | Average retirement income | Annual spending gap | Weekly spending gap |
| Essential – single | £13,000 | £18,900 | £5,900 | £113 |
| Essential – couple | £18,000 | £22,500 | £900 | £17 |
| Comfortable – single | £19,000 | £18,900 | -£100 | -£2 |
| Comfortable – couple | £26,000 | £22,500 | -£7,100 | -£137 |
| Luxury – single | £31,000 | £18,900 | -£12,100 | -£233 |
| Luxury – couple | £41,000 | £22,500 | -£22,100 | -£425 |
How much do I need for retirement & where do I get it from?
First, I will do this from a U.K perspective, the current full state pension, is at 179.60 GBP with a 35-year contribution of national insurance, for those retiring in a few years have a triple lock that will go up with inflation.
To quickly, go over the state pension it currently works out at around 5 GBP for every year contributed and you have a maximum of 35 years contribution. If you have any less than this it is done on a pro-rata basis.
One point, that is relevant to a lot of expats is that you can contribute to either class 2 or 3 depending on your situation.
More information on this can be found in the link below:
https://www.gov.uk/new-state-pension/living-and-working-overseas
Investments For Expats top tip, if you can contribute to class 2 you are putting in just over 3 GBP to get 5 GBP back.
Another factor you have to think of is your private pension, normally you have two types of workplace pensions defined benefit this pays you a set income depending on your length of service and your salary.
They are also mostly inflation-linked. These days they are normally only in the public sector and are very rare.
The other one that is most common is defined contribution pensions, these payout the value of the pension pot. They are normally invested in a group scheme unless you have taken them out which is more commonly known as a SIPPs
Other factors that are likely to make rental income if you have a property or private savings and investments.
The important question is how much do you need to save?
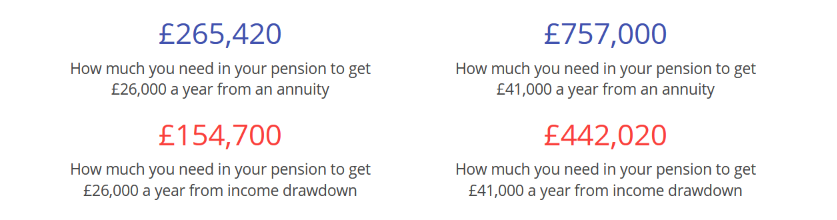
Again this depends on what lifestyle you are looking to have. It is illustrated in the table below, that the average income for a modest retirement for a single person is 26,000 GBP a year is 265,420 GBP if put in an annuity. Raising to 757,000 GBP for a deemed luxury lifestyle deemed by Which? 41,000 GBP would need 757,000 GBP lump sum.
Table 4- shows how much is needed to be saved to get to 26,000 GBP and 41,000 GBP if you were to put in an income or annuity.
Saving based on age?
Which? also, did some interesting calculations that suggest what you will need to save each month depending on your age, at 20, 30, 40 and 50.
What Which? does present is that the earlier you save the less you need that goes with what Einstein coined the 8th wonder of the world, compound interest.
Table 5- shows how much couples need to save every month if they have 100,000 GBP of savings and no savings to have what Which? deem a comfortable retirement 154,000 GBP. and below what they deem a luxury retirement.

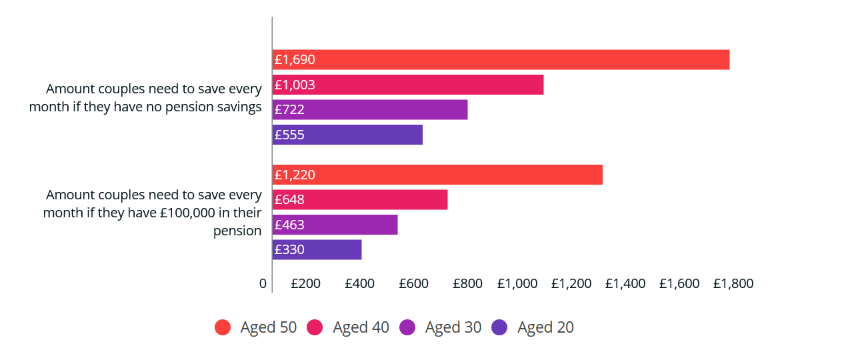
As seen above in both tables, it can significantly increase the later you leave your saving at least trebling from leaving it in your 50 to starting in your 20s.
Final thoughts
This study does emphasise the need to start saving early, some criticisms with the study is that it hasn’t factored in true CPI inflation, that for someone in the 20s and 30s might be in real terms a lot more than projected figures of 2.5% annual.
Also, people need to factor in life expectancy, as it keeps increasing, when pensions were first introduced it was factored that only 5-10 years were needed now with retiring at 65-67 can realistically look 20+ years of needing to fund yourself.
Lastly, this is a U.K study based on U.K income and outgoings as illustrated by the cost of living site Numbero, it is possible to live in countries with a lower cost of living such as South East Asia. So, might want to factor that for a cheaper retirement.
For more information, I have written blogs on the FIRE movement. If you have any questions and would like to speak to me, please email info@investmentsforexpats.com