What do you think the tax rate is going to be by the time you turn 59.5 years old? Is it going up, down, the same as of 2018 which is the year of this answer?
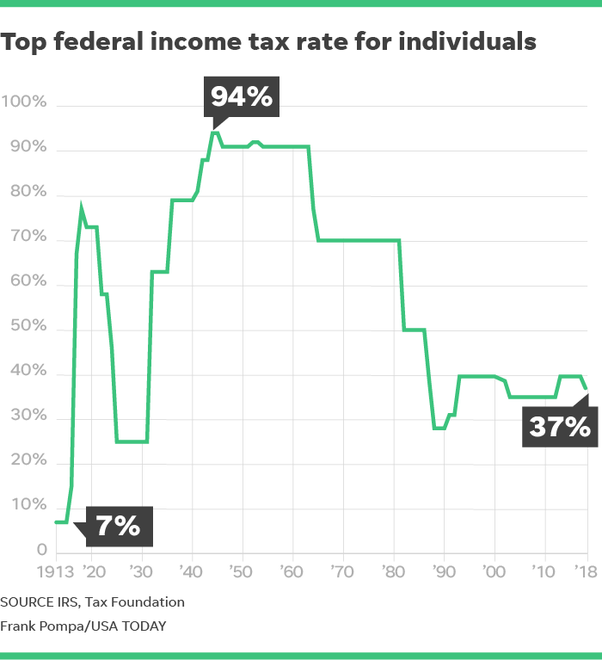
No one has a crystal ball to know for sure. However, just so you know where our tax rates have been since the inception of the tax code back in 1913, here it is:
So as you can see had the Roth been invented back in the ’40s then perhaps it wasn’t a good idea for those of you who started taking out distributions in the late ’80s, early ’90s when the top marginal tax rate was way lower than that in the ’40s.
Also, if you study the graph, the tax rate actually went up a bit as recent as 2013 for about 4 years until it came back down again in 2018. The point I’m trying to make is that you can certainly speculate what’s going to happen 30, 40 years out as far as what tax table you’re going to use but that’s just speculation.
You have zero control whatsoever what your tax is going to be. The government does and this should put you on edge.
Some people could even go as far as arguing that they know without a doubt that their tax bracket is going to be in the 10% (the lowest bracket) because by that time they stop working, so the only income they have is Social Security and 401(k) distribution.
In theory, this argument sounds very convincing until you discover that you’re going to live in poverty for the rest of your life, which is not something most people want. Yes, to have a low tax bracket your income must be less, and if you’re accustomed to the lifestyle you had before your retirement when you made more income, how long do you think you’re going to last before you decide you can’t suffer this low-income lifestyle anymore?
Most retirees would like to travel the world, go around the country to visit family, and do things that require money like buying gifts for their grandchildren on their birthdays, go on a cruise, pay property tax (if they own a house, if they don’t own, they still have to pay rent). It is true they no longer need to pay their mortgage if they already paid off their house but in place of it is medicare related expenses such as medicare supplement premium, co-pays for medicine, and health-related stuff that they never needed when they’re younger.
Furthermore, most retirees do not necessarily stay home all day. So the group that argues their tax rate in retirement will definitely be in a lower bracket than before retirement, well, I wish them luck in living that lifestyle. For me, personally, I’d like to maintain the same standard of living if not more extravagant during my retirement years because darn it, I’ve earned it.
Therefore, I do not count on the argument of a lower tax bracket in retirement years with the assumption that the tax table will stay the same when I retire, which I have no control over.
Secondly, now that you get the projected tax rate critical question taken care of, the next question is if you never need money from your Traditional IRA in retirement because you have other sources of income to draw from, can you be forced to take out the money when you turn 72 years old? The answer is yes.
Forced withdrawal is also known as RMD (Required Minimum Distribution). Since you’re forced to take it whether or not you need it, it is likely that it will throw more of your social security income into the taxable territory.
With a Roth, there isn’t any RMD so when you don’t need money from the Roth you don’t have to pay more taxes on your social security income. So with a Roth, you have a bit more control over how your social security income is going to be taxed in the future.
If you want to talk to me or have any questions on this topic then please email me at info@investmentsforexpats.com