
Most offshore advisory companies structure their fees in a way using the same third parties to hold the pensions. Most of these can be costly and potentially have hidden fees.
This adds up to create multiple layers of fees that continuously erode your pension fund. Therefore finding a cost-effective option is important when considering the options of what to do with your pension(s). As, some offshore companies are structured in a more complicated way and can be designed to hide the true cost to the client. I have done a full review of the companies and what options you have.
I will state the cost that you have, but before I go too much further, I would advise looking for 1% initial and 1% ongoing as a benchmark cost.
Figure 1: Is an illustration of the cost of transferring your pension(s) and the different layers involved in offshore pension transfers.

Pension Report Charge:
This is a simple fee, charged upfront to the client. This is only applicable in the instance that a pension is being transferred from a Defined Benefit (DB) Pension and has a value of over £30,000. In this case, the client is required by law to receive an independent report from an FCA regulated advisor that holds report writing permissions.
The total charge will depend on the report writing company that the advisor has terms of business with. In the offshore market, provisors such as Onvestor are charging 3,500-4,000 GBP (2022) for a report.
Trustee Fees:
A pension must be transferred to another pension. The trustee acts as the wrapper around the platform where the funds are invested in order to ensure the funds are managed in line with pension rules. For example; making sure no funds are withdrawn before the age of 55. Trustee fees vary depending on which trustee is being used.
I have written a number of my articles and most will tell you that the cheapest in the offshore space is Novia at 180 GBP a year. It is worth noting that Trustee costs can add up as they can have charges associated with withdrawals, initial set-ups and admin costs that can go way above the initial annual fee.
Platform/Bond Charge:
Once the funds are transferred they are typically held in an investment vehicle that facilitates the buying and selling of assets such as funds and stocks. There are low cost platforms that make their money by charging a dealing charge, which is a fixed amount for transactions. Portfolio Bonds or Personal Bonds, are often used by advisors as they facilitate commissions paid back to the advisor.
Fund costs:
ETFs (Exchange Traded Funds) are the cheapest option as there is a lower cost associated with running the fund, they also do not pay commissions. ETFs typically cost anywhere between 0.10%-0.30%.
Managed funds can cost anywhere between 0.50%-5%, with an average cost of around 1.5%. Funds costing over 1% are often paying a commission back to the advisor. This fee is not shown as a fee, rather the fund will declare its performance net of fees, making it hard for clients to see what they are actually paying.
A tip on this is to look up the ISIN number on Morningstar and look at the fund cost. If an advisor is looking at an active fund (especially one that is not well known with high fees) I personally would question it. Sticking to low-cost ETFs can be fine, however, it does depend on your financial and current circumstances.
Conclusion
Fees add up over time and calculating the true cost of fees can be difficult. A pension that has been transferred into a Bond by an advisory company has very little chance of achieving any growth, due to the high fees. The situation is worse for clients that have a cautious approach to investing.
A cautious portfolio can be expected to return 3-4% per year. But if 1% is being taken as an advisor fee, 1% as a platform charge, another 1% from the growth of the funds and then the fixed
charges on top of that for the trustees, the portfolio is likely to go downwards over time.
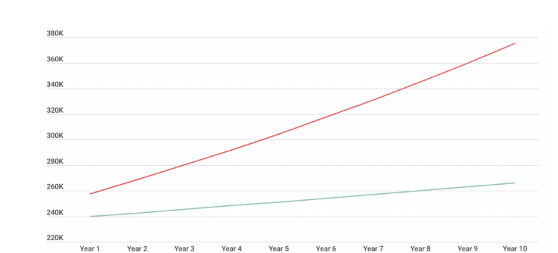
The chart below shows the difference between a high-cost solution and a low cost one such as the IFE model, on an initial investment of £250,000 and an assumed growth rate of 6% per year.
Figure 2: Illustration of how pension costs erode gains over a 10 year period on 250,000 pensions at an assumed 6% growth rate.
Our IFE Model
The IFE model is simple, transparent and fair on pension transfers. Whether you want to transfer a pension or have already transferred and you want to reduce your fees, IFE offers a solution that is inline with UK best practices.
Our fee is 0.5% per annum, 0.3% Platform costs and 180 GBP trust small annual fund cost of around 0.15%. No more. This means your fees stay near or below 1% (for anything over 100,000 GBP).
We don’t hide charges on pension transfers from you and don’t charge any extra for pension administration, trading commissions or drawing down your pension.
If you want to ask any questions regarding pensions, the costs or transferring it offshore as an expat because you aren’t sure of the process to follow, please email me and I will be happy to set up a call. Please email me at info@investmentsforexpats.com.


