Transferring a pension can be complex, especially for UK expats who need to navigate various platforms and their intricacies. For years, the “Gold Standard” advice for UK expats was simple: Leave your pension untouched. Because pensions sat outside your estate for Inheritance Tax (IHT) purposes, they were the most tax-efficient way to pass wealth to the next generation.
That era is ending.
From April 6, 2027, the UK government will officially bring unused pension funds and death benefits into the value of your taxable estate. This isn’t just a minor tweak; it is a fundamental shift that could see your beneficiaries lose up to 40% of your pension pot to HMRC before they even receive a penny.
Below is an overview of five popular UK pension transfer platforms that I believe are some of the best options as of 2026 to serve expats: Novia SIPPs, IPensions, MyExpat SIPPs, RL360/IGFL, and Invinitive. The article’s key focus areas of the article include costs, regulation, and reputation.
I have used a number of these platforms, and I will give my perspective on how I have found them and an honest, non-biased option.
If you have any questions, please contact me by using the button at the bottom of the page or via my contact page.
New Tax Rules for Expats (5th April 2027)
What this means for Expats in 2026:
- The Double Tax Trap: If you die after age 75, your heirs could face a combined tax rate of up to 67% (40% IHT on the pot, plus their own marginal income tax rate on withdrawals).
- Frozen Allowances: With the Nil-Rate Band (£325k) frozen until 2030, more expat pensions than ever will fall into the tax net as fund values grow.
- The “Tail” of Residency: Under the new 2025 residency-based system, even if you’ve lived abroad for years, your UK pension assets remain firmly in the crosshairs of the UK taxman.
If you are currently holding a UK SIPP or a Frozen Final Salary pension, you are sitting on a “ticking tax bomb.” Reviewing your platform options and considering a transfer to more flexible, international structures is no longer about saving a few basis points on fees; it is now about protecting your family’s inheritance.
Platforms for Pensions
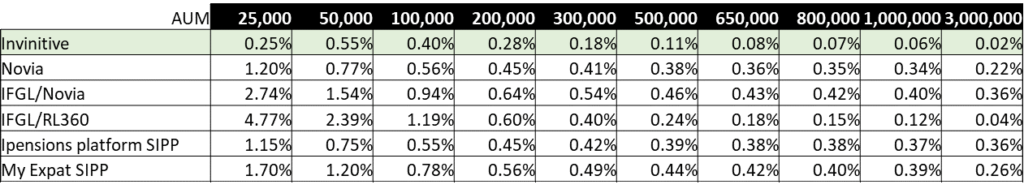
The table below shows the cost of the main SIPP transfer platforms in the expat options
Novia SIPPs
Overview: Novia SIPPs is a part of Novia Financial, a platform that specialises in Self-Invested Personal Pensions (SIPPs) among other financial services.
Costs: Typically, Novia charges a fixed setup fee along with annual management fees, which vary depending on the total assets under management. Transactional fees might also apply to specific investments.
Platform Fee (Tiered): * 0.30% on balances up to $1M.
- 0.20% on the next $1M.
Annual SIPP Fee: £260 per year
Custody Fee: 0.04% per annum (standard across all accounts).
2026 Change: They have heavily improved their automated drawdown features, making it the best option for those needing monthly GBP income while living abroad.
Regulation: Novia is regulated by the UK’s Financial Conduct Authority (FCA), ensuring adherence to high standards of client protection and financial management.
Reputation: The platform is well-regarded for its robust investment options and comprehensive management tools. Clients appreciate its transparency and tailored service, especially appealing to experienced investors looking for diverse choices.
the-international-sipp-brochure.pdf (novia-global.com) and Novia website.
RL360/IGFL
Overview: RL360, in partnership with International General Finance & Life Limited (IGFL), offers a wide variety of investment products, catering to expats worldwide.
Costs: RL360’s fee structure can vary significantly, including initial establishment fees and ongoing management charges; specific costs depend on the chosen investment products. IFAs often use this for commission, and it can be complicated to understand the charging structure. I will put a link below to an article that goes over the fee structure. On a 10-year plan, the base cost is 0.067% a year for 10 years and a 400 GBP admin fee. With the 7% upfront fee (which is mostly paid to the advisor) 1% for 10%, and 400 GBP. Please read the article below about the charging structure and commission:
Regulation: Operating out of the Isle of Man, RL360 is regulated by the Isle of Man Financial Services Authority, which ensures compliance with international standards.
Reputation: The platform has a strong international presence and is recognised for its diverse range of investment options and flexible terms. Its services are generally well-received by expats seeking comprehensive solutions.
However, personally I found the platform very slow and the costs expensive. THIS CAN BE A COMMISSION-BASED PRODUCT, so the fees can vary depending on the IFA charges. The base cost is 0.067% plus 400 GBP on a 10-year plan.
I would look at other options for most expats, as an offshore bond has little or no effectiveness in a SIPP and with cheaper platform options with significantly better platforms and much lower dealing fees (40 GBP compared to 5 GBP). I do not see RL360 as a viable option for most expats, and it would generally be proposed by IFAs on a commission basis, which is not FCA-regulated. You can also go into fee-paying funds, which are not viable with other FCA-regulated platforms that I have listed above.
IPensions
Overview: IPensions focuses on providing retirement solutions, including SIPPs aimed specifically at expatriates who require flexible investment and management options.
Costs: IPensions generally have a competitive fee structure, with setup and ongoing annual fees. They offer clear, upfront pricing, which can include fees for additional services.
Regulation: The platform is also regulated by the FCA, underscoring its commitment to secure and reliable pension management services.
Reputation: IPensions is known for its strong customer support and efficient processing times, making it a favoured option for those seeking smooth international pension transfers.
Award-Winning Personal Pensions | iPensions Group
MyExpat SIPPs
Overview: As the name suggests, MyExpat SIPPs are tailored for expatriates needing to manage their pensions while residing abroad. It offers simple and efficient solutions.
Costs: The fee structure includes initial setup fees and annual management fees, with potential charges for fund switches or specific investment choices.
Regulation: They operate under the regulation of the FCA, providing clients with peace of mind regarding the security and integrity of their pensions.
Reputation: Clients often praise MyExpat SIPPs for its user-friendly interface and personalised customer service, helping them make informed investment decisions from afar.
Online International SIPP Pension for Expats and Non-UK Residents (myexpatsipp.com)
Invinitive
Overview: Invinitive provides specialised financial services and pension solutions tailored for expats and individuals with complex pension needs.
Costs: Their pricing structure involves setup fees and periodic management charges, often determined by the total value of assets held.
Platform Fee: 0.25% flat.
Platform Cap: Still capped at £400 per year (making it incredibly cheap for £200k+ pots).
SIPP Admin Fee: £0 (They absorb the trustee costs into the 0.25%).
2026 Change: Be aware that Invinitive is still a smaller firm. While safe under FCA rules, larger investors often prefer the “institutional” feel of Novia or Morningstar.
Regulation: Invinitive adheres to FCA regulations, ensuring they meet the rigorous standards expected within the UK’s financial services.
Reputation: Known for its expert advisory services, Invinitive is appreciated for its strategic approach to pension management, making it a reliable choice for those seeking personalised financial strategies. It’s a new platform starting in 2023; however has become very popular in the offshore space due to its low fees and easy admin.
British Expat SIPP, Low Cost, All Digital Platform, Zero Paperwork. (invinitive.co.uk)
My Top pick for 2026:
Firstly, with all the exceptions other than RL360, the platforms listed above would state that these are all okay options to transfer your pension overseas, as all have competitive pricing and an FCA-regulated fee-paying structure. I would also add the Morningstar platform as a viable option (with a separate low-cost trust) for clean fee-based platforms.
Morningstar is often used by high-net-worth expats who want deep research tools and institutional-grade security.
- SIPP Setup Fee: £195 (one-off).
- Annual Trustee Fee: £195 per year.
- Platform Fee: Typically 0.25% – 0.35%, depending on the specific model portfolio used.
- 2026 Change: They have introduced a “Full Wrapper Suite” in 2026, allowing you to link your International SIPP with an ISA (if you still have UK ties) on one dashboard.
However, after using most of the platforms. One of the best options is Invinitive.
Pros of Invinitive:
- Cost Effectiveness: With no IPP fee for smaller accounts and a capped platform fee for larger ones, Invinitive offers transparent and favourable pricing. This is particularly beneficial for individuals with varying account sizes and transaction needs.
- Transparent Pricing: Clear communication about fees without hidden charges makes it easier for clients to manage their investment costs effectively.
- Flexibility in Investments: Competitive trading fees encourage flexibility, allowing investors to buy and sell without prohibitive costs.
- No Benefit Costs: The absence of costs for specific pension benefits underlines Invinitive’s commitment to cost efficiency.
Cons of Invinitive:
- Trading Fee Structure: While competitive, the flat trading fee could add up for frequent traders compared to platforms offering lower fees per transaction or percentage-based trading costs.
- Limited Brand Recognition: Compared to more established platforms like Novia, which have extensive international recognition, Invinitive might not have the same brand strength or widespread customer reviews.
Personal Perspective (Conclusion)
In my opinion, Invinitive is currently one of the best platforms available for UK pension transfers, primarily due to its efficient administrative processes and competitive pricing structure. Many platforms in the market struggle with administrative delays, leading to slow application processing and trading delays. However, Invinitive excels in this regard, offering a streamlined application process and allowing trades to take place promptly, enhancing the user experience significantly.
Furthermore, the simplicity of the cost structure—particularly the capped fees and absence of hidden charges, makes Invinitive exceptionally appealing to a wide range of investors. This transparency and efficiency, combined with competitive costs, make Invinitive a compelling choice for those seeking a hassle-free and cost-effective pension transfer platform.
In summary, if you are looking for a reliable, fast, and cost-efficient option for managing your UK pension as an expat, I strongly believe Invinitive should be one of the top options.
| Platform | Annual SIPP Fee | Platform % Fee | Best For… |
| Novia Global | £260 | 0.30% (Tiered) | Multi-currency & Drawdown |
| Invinitive | £0 | 0.25% (Capped at £400) | Low cost / Smaller pots |
| Morningstar | £195 | 0.25% | Research & Security |
| Interactive Investor | £12.99/mo | £0 (on first £50k) | DIY / Fixed Fee Fans |
Blogs that will help you with your pensions:
- Understand the New UK Pension Allowances and Their Effects on Expats
- Comparing Platforms – Novia vs Morningstar for Expats
- UK Expats Self Invested Pension (SIPPs)
- Transferred Your Pension Offshore?
Yes, but the goal has shifted. Previously, transfers were about lower fees; now they are about IHT planning. With UK pensions being pulled into the IHT net in 2027, moving to a modern International SIPP or QROPS allows for better control and potential tax-shielding strategies.
Yes, you can perform a “Drawdown to Drawdown” transfer. Platforms like Novia and Invinitive are specialists in this, allowing you to move your “pot” even if you are already receiving an income, often with much lower administrative fees than traditional UK providers.
While some UK ceding schemes still use “paper-based” hurdles, digital-first platforms like Invinitive have reduced transfer times to 3–5 weeks. However, if your current provider is a “Defined Benefit” (Final Salary) scheme, the process can still take 3–6 months due to mandatory advice requirements.